Where the Property Fund Idea Came From
Where the property fund idea came from: trace the documented milestones behind collective property ownership and distinguish early arrangements from modern funds.
The common mistake when asking where the property fund idea came from is to treat every form of shared property ownership as an early fund. That turns a useful history into a misleading origin story: family co-ownership, business partnerships and regulated investment products are not interchangeable. A clearer account starts with documented milestones and keeps each arrangement in its own legal and historical setting.
What counts as a property fund in this history?
For this article, a property fund means an organised arrangement that pools contributions from participants to acquire or hold property, with a defined way to manage assets and account for participants’ interests. This is a working description, not a legal definition. The formal meaning of “fund” depends on the place and period being discussed.
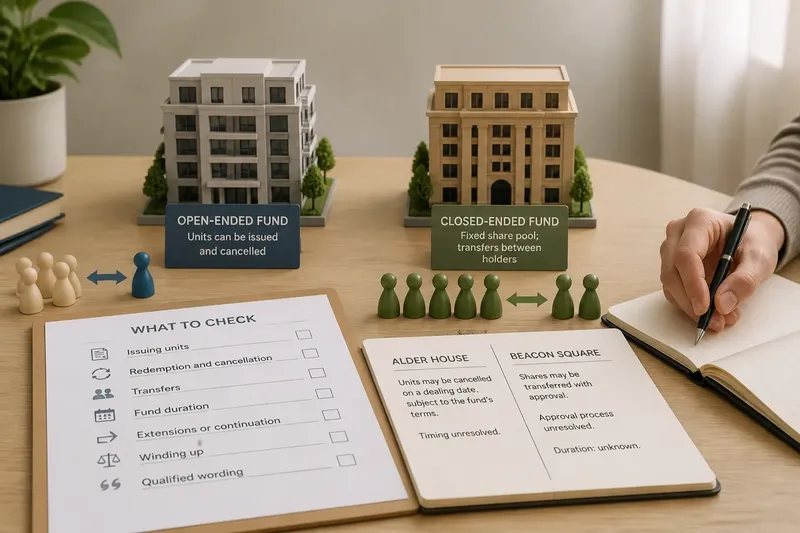
Shared ownership alone is not enough. People may jointly own land through inheritance, family arrangements or community practice without pooling resources for investment or delegating management. A business partnership may share property and profits, yet differ from a modern fund in its legal status, participant rights and oversight.
That distinction sets the scope: trace arrangements that show identifiable features of pooled property ownership, and avoid naming them as modern funds unless the evidence supports that description.
Which historical milestones can be stated clearly?
There is no single global sequence. The available history depends on a specific place, its law and the records that survive. A sound account should therefore name the jurisdiction and date for any claimed milestone, then explain precisely what changed.
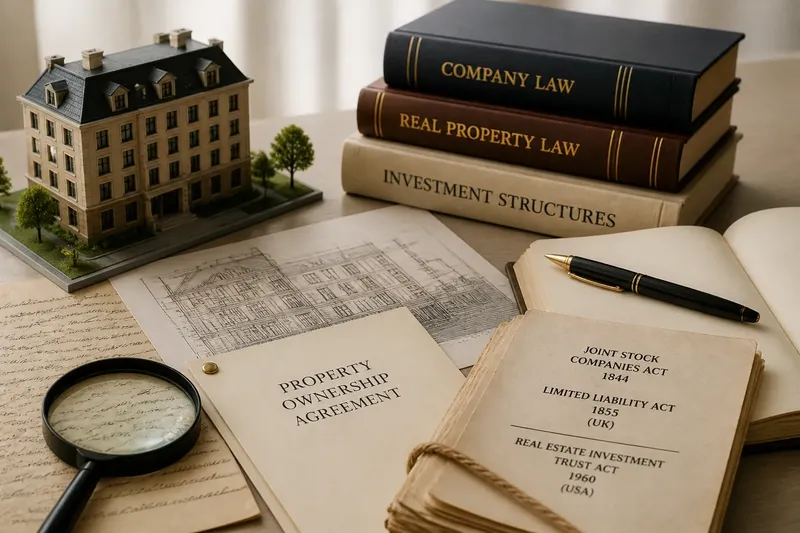
In England, the Joint Stock Companies Act 1844 introduced a process for company registration, while limited liability was addressed separately by the Limited Liability Act 1855. These were milestones in company law, not the launch of property funds. They help explain the development of business forms that could hold assets and organise shared interests, but they do not establish one universal origin for collective property investment.
In the United States, Congress created the real estate investment trust framework in 1960. This is a specific statutory milestone for a named modern structure. It should not be presented as the origin of all property pooling: other collective arrangements and legal forms existed in different contexts, and a REIT’s rules and operation depend on applicable law.
These examples are useful because they separate three things often blurred together: longstanding shared ownership, company-law mechanisms and a defined statutory investment vehicle. They are milestones in particular jurisdictions, not a complete history of every country’s property arrangements.
What problem did pooling address?
A building can require contributions for acquisition, upkeep and management that one participant may not provide alone. Pooling gives several participants a way to take part, while an agreed structure can assign practical decisions to a manager or governing body.
Think of a shared property arrangement like a communal pantry: contributions and responsibilities need to be recorded so everyone knows what is held and how it is managed. Property adds legal rights, income and losses, so a record-keeping analogy cannot explain the full arrangement.
As participation became more organised, written rules could specify contributions, decision-making, management duties and how proceeds were allocated. The exact form depended on local law and commercial practice. The historical point is not that one structure inevitably replaced another, but that different structures addressed related organisational problems.
How did company forms differ from modern funds?
A partnership or company can help several parties own or manage property, but neither is automatically a property fund. A partnership may set out contributions and shared responsibilities. A company may hold assets in its own name and record ownership through shares, subject to the relevant law.
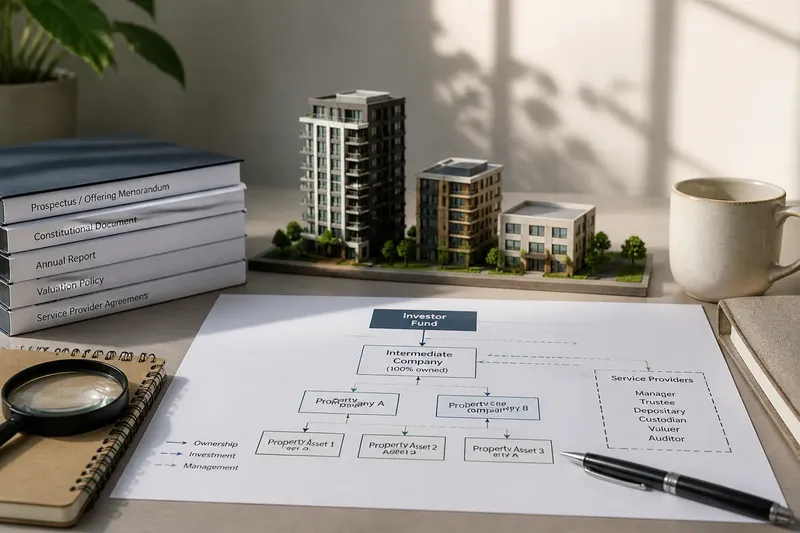
A modern fund may use a company, trust or another legal vehicle, but the label alone does not settle how participants’ interests work. The offering documents, governing rules and local regulation define important features, including who makes decisions and what rights participants hold.
When reading a historical account, distinguish the legal container from the investment arrangement. A company could be used for many purposes; a collective investment product is defined by more than the fact that a company owns property.
How should you check a claimed origin?
Take each claim apart before repeating it. Identify the place, date, legal form and feature said to have begun. If a source calls something “the first property fund”, check whether it means the first example of pooled ownership, a new company form, a statutory category or a widely used product.
- Check the place. If the claim names a country or jurisdiction, compare it only with developments in that setting; if it does not, treat it as a limited claim until a location is established.
- Check the date and source. If the source gives a dated primary record or legislation, use that date for the specific event; if it gives neither, describe the origin claim as unverified rather than repeating it as fact.
- Check what “first” means. If the source identifies a first statutory vehicle, describe that legal milestone; if it means an earlier shared arrangement, do not call it a modern fund without supporting evidence.
- Separate practice from law. If evidence shows a customary or private arrangement, describe it as practice; if it identifies legislation, name the law and the change it made.
- Identify the feature that changed. If the evidence concerns pooled contributions, say so; if it concerns management, ownership records or regulation, name that feature instead of calling the whole arrangement a new fund.
- Check the terminology. If a historical source uses a label in a clearly defined way, preserve that period-specific meaning; if the term’s meaning is unclear, explain the uncertainty rather than applying today’s definition.
For example, imagine a reader finds an undated article claiming that a nineteenth-century company was “the first property fund”. The reader checks the company’s registration record and finds its jurisdiction and date, then checks the source’s wording against the company’s documented purpose. If the record confirms only that it was a property-holding company, the answer is to describe it that way—not as the first modern fund. If a separate source identifies a statutory investment category, that can be discussed as a different milestone.
Which questions clarify property fund origins?
Did shared ownership always mean investment?
No. Property could be held jointly for family, community or business reasons without being organised as an investment product. Purpose, participant rights and management arrangements help distinguish these cases.
Does a company that owns buildings count as a fund?
Not by that fact alone. A company may hold property for many reasons, so check its purpose, ownership arrangement and applicable legal classification.
Can one country’s history explain the whole idea?
No. A country’s laws can explain a particular legal route, such as a statutory vehicle or company form, but not every tradition of collective property ownership. Keep national milestones attached to their jurisdiction.
What is the safest way to describe an old arrangement?
Use the terms supported by the source and identify the particular feature that matters, such as joint ownership or pooled contributions. Avoid a modern fund label unless the evidence establishes that comparison.
How does this history help with fund descriptions today?
The history clarifies why “property fund” is not a single timeless design. Shared property ownership, company law and statutory investment structures each have distinct histories; a resemblance between them does not establish identical rights or oversight.
When a fund description invokes history, check the specific connection it claims: pooled capital, shared ownership, delegated management or a legal category. Where rights or obligations matter, consult the governing documents and seek a qualified professional if needed. The phrase “where the property fund idea came from” is most useful when it leads to a precise question about which place, period and structure the source actually means.