Open-Ended and Closed-Ended Property Funds: How Units and Fund Life Differ
Compare open-ended and closed-ended property funds by tracing unit changes and fund duration, so you can distinguish dealing arrangements from a fund’s intended life.
The common mistake with open-ended and closed-ended property funds is to read the labels as a promise about how easily you can leave. That can blur two different questions: what happens to units, and what happens to the fund over time.
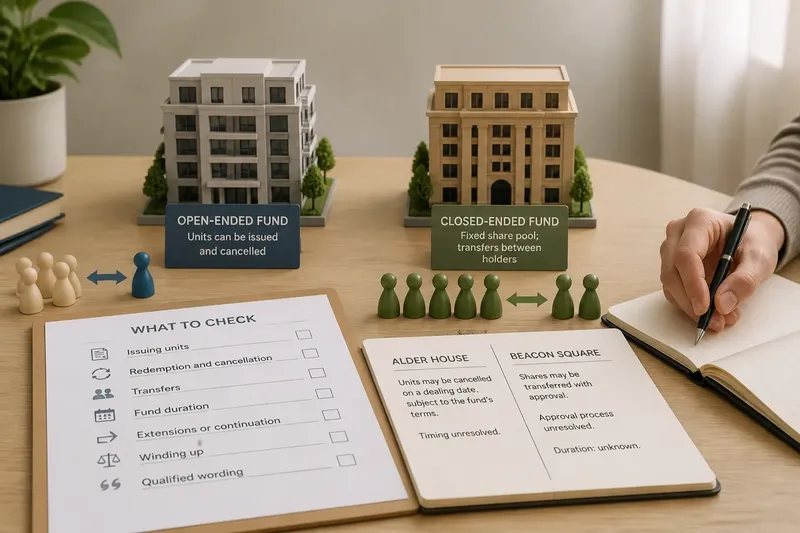
Say you are comparing two invented funds, Alder House and Beacon Square. Alder’s description says it can issue and cancel units under stated arrangements; Beacon’s says its share pool is fixed. To compare them, trace a unit from creation to transfer or cancellation, then look separately at each fund’s duration and closure arrangements.
What do the labels tell you about units?
In broad terms, an open-ended fund can issue units when investors subscribe and cancel them when investors redeem, subject to its terms. A closed-ended fund generally has a set pool of units or shares; an investor seeking to leave may need to transfer an existing holding to another person.
Those descriptions are not instructions for how quickly a transaction happens. The terms may set dealing dates, notice requirements, restrictions or other conditions. A transfer also depends on the fund’s rules and the arrangements for finding a buyer. The labels alone do not tell you whether an exit is available at a particular time.
Think of units as seats on a bus. One arrangement can add or remove seats as passengers join or leave; another has a set number of seats, so a departing passenger looks for someone to take their place. The analogy helps distinguish unit mechanics, but it does not explain the fund’s full rules or the value of a holding.
How might an open-ended fund handle units?
In the invented Alder House description, new subscriptions may lead to new units being issued, while redemption requests may lead to units being cancelled under the fund’s terms. Its unit count can therefore change. The description does not, by itself, say that every request will be processed immediately or on the same basis.
When reading an open-ended fund’s terms, look for how an investor submits a request, when requests are dealt with, and whether the documents describe limits or circumstances in which dealing may be paused. Note the wording around discretion: “may” and “subject to” can signal that an apparent promise has conditions.
How might a closed-ended fund handle a transfer?
In the invented Beacon Square description, the fund has a set pool of shares. A holder who wants to leave may need to find someone willing to take those shares, if transfers are permitted. In a transfer, ownership moves between holders; that is different from the fund cancelling shares and returning capital under a redemption arrangement.
Imagine Beacon’s fictional documents allow transfers, and a holder wants to sell to another person. The holder follows the stated transfer process; if it is completed, the other person becomes the holder and the fund’s share pool remains in place. If the documents restrict transfers or no buyer is available, the route may be less straightforward. This scenario illustrates the distinction, not a prediction about any real fund.
How do fund duration and unit arrangements differ?
Unit arrangements describe how units are issued, cancelled or transferred. Fund duration describes the vehicle’s intended life and what its documents say about its end. One does not supply the answer to the other.
A closed-ended fund may have a stated term, an extension process or another way of considering continuation. An open-ended label does not, on its own, state how long the fund is intended to operate. For either type, look for the language on winding up and the treatment of assets. Do not infer an end date or a particular outcome from the label.
For Alder and Beacon, a useful comparison would record what each description says about unit dealings and duration in separate columns. If Alder’s summary explains that the number of units can change but says little about redemption conditions, mark that as an unanswered question. If Beacon’s summary describes a fixed share pool but says little about transfers or closure, mark those points separately. This keeps the comparison focused on the terms rather than on assumptions about which arrangement is better.
What should you check when comparing the terms?
- Issuing units: Check whether the documents describe new units being issued and what process applies. If the process is stated, record it; if it is missing or unclear, mark issuance mechanics as unresolved.
- Redemption and cancellation: Check whether holders can ask the fund to cancel units and which conditions apply. If dates, notice or restrictions are stated, record them; if not, do not assume redemption is available on demand.
- Transfers: Check whether a holder can transfer units or shares and whether approval or other conditions apply. If transfers are permitted, record the stated route; if restricted or unclear, treat transferability as unresolved.
- Fund duration: Check whether a term or end date is stated. If one appears, record it as the document’s stated duration; if none appears, do not infer one from the fund label.
- Extensions or continuation: Check whether the documents describe how an extension or continuation is considered. If they do, note the stated process; if they do not, leave the outcome open rather than assuming the fund must continue or close.
- Winding up: Check what the documents say about closing the fund and dealing with its assets. If a process is described, summarise its stated stages; if it is not, note that the end-of-life arrangements remain unclear.
- Qualified wording: Check for terms such as “may”, “subject to” and “at the manager’s discretion”. If they qualify a statement, carry that qualification into your comparison; if the wording is ambiguous, do not turn it into an unconditional promise.
Say you have two invented summaries. Alder’s says, “Units may be cancelled on a dealing date, subject to the fund’s terms,” but gives no dealing date in the summary. Beacon’s says, “Shares may be transferred with approval,” but does not explain the approval process. First, record Alder’s unit route as cancellation subject to terms, with timing unresolved. Next, record Beacon’s route as transfer with approval, with the approval process unresolved. Then compare their duration wording separately: if either summary is silent, mark that point as unknown rather than filling it in. The resulting comparison distinguishes what the summaries state from what they leave unanswered.
What questions clarify open-ended and closed-ended property funds?
Does open-ended mean I can redeem whenever I want?
No. The label describes a broad unit framework, not a personal right to redeem at any time. Check the fund’s terms for request procedures, dealing arrangements and conditions.
Does closed-ended mean the fund has a fixed end date?
Not by itself. The documents explain duration, any extension or continuation process, and how the fund may be wound up. Read those provisions separately from the unit label.
Is transferring a closed-ended share the same as redeeming an open-ended unit?
No. A transfer moves an existing holding between people, while cancellation or redemption involves the fund acting under its arrangements. The particular process depends on the documents.
Can the labels tell me how easy it is to exit?
No. They do not establish whether a transaction is available, when it can happen or what conditions apply. Compare the specific transfer or redemption provisions instead.
How should you record the comparison?
Keep the final note brief and separate the categories. For each fund, write down the stated route for issuing, cancelling or transferring units; the conditions attached to that route; the stated duration; and what the documents say about closure. Use “not stated” where the description leaves a gap.
That method makes open-ended and closed-ended property funds easier to compare without treating either label as an exit promise. If an important term remains unclear, preserve the question and ask an appropriate professional to explain the documents before relying on an interpretation.