What a Property Fund Structure Tells You
Understand what a property fund structure describes, trace ownership and decision-making, and separate confirmed details from unanswered questions in fund documents.
The common mistake with a property fund structure is to treat its label as a verdict: “property fund” sounds like a complete description, so a reader assumes they know what they would own and how it would be managed. That shortcut can obscure the actual arrangement. A structure describes how a fund is organised; it does not, by itself, establish suitability or likely outcomes.
Instead of following a day-by-day reading routine, trace the fund’s legal entities, responsibilities and stated property interests. Keep confirmed details separate from unanswered questions. This is general information, not investment advice; consult a qualified financial or legal professional if a decision depends on your circumstances or interpretation of formal terms.
What does the property fund structure label tell you?
A document may describe a trust, company, partnership or another legal form. It may also mention an umbrella arrangement, feeder vehicle, master fund or property-holding subsidiary. These terms answer different questions: one may identify the legal vehicle, while another describes how investment exposure is channelled towards property.
Start with the exact wording in the current formal documents. Note the document title and date, then identify the entity that issues the shares, units or other stated interest. Do not assume that an investor-facing fund owns buildings directly simply because its name refers to property.
For instance, “investment trust” may prompt the question of which entity issues the shares. “Property company” may prompt a different question: does the fund own the buildings, or does it hold shares in a separate company that does? Keep each question open until a formal description or provision answers it.
How can you trace ownership and responsibility?
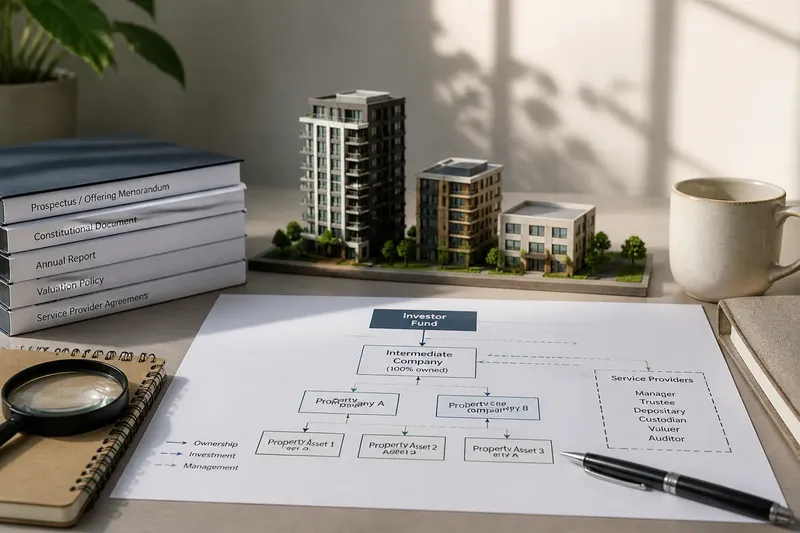
Draw a simple map with boxes for entities and arrows for relationships. Begin with the investor-facing vehicle, then add each named subsidiary, holding company, property company, feeder or master fund. Label an arrow as ownership, investment or management only when the documents support that description.
Place service providers in separate boxes. A manager, trustee, depositary, custodian, board and general partner are not interchangeable labels. The documents define their roles, powers and limits; a title alone does not establish the extent of someone’s authority or oversight.
Say you are reading a fund description that names a fund, a wholly owned intermediate company and property-owning entities beneath it. Your map would show each as a separate box, with ownership arrows only where the documents state that relationship. Next, mark the named decision-makers and the stated borrowing entity. The resulting map should make clear which relationships are documented and which remain uncertain; it does not show whether the arrangement is better or worse.
Which documents clarify the arrangement?
The prospectus or offering memorandum can describe the vehicle, objectives, material risks and terms. The constitutional document sets out governing arrangements. A report describes holdings, service providers or financial position as presented at its reporting date. A diagram can make relationships easier to see, but it does not replace the formal wording.
Compare entity names and roles across the documents. If one page names a subsidiary while another gives only the fund’s name, record the gap instead of filling it in from context. Check defined terms such as “fund”, “company”, “manager” and “property”: a familiar word can have a specific meaning in that document. If the discrepancy affects your understanding, seek a written clarification from the provider or advice from a qualified legal professional.
Trace how the documents describe property exposure. The fund may own property directly, hold shares in property companies, invest through another fund, or combine these routes. Distinguish the investor’s stated interest—such as a share, unit or partnership interest—from the underlying property. A fund name can signal a theme without spelling out the route to the assets.
Also note what the documents say about valuation and reporting. A valuation policy describes how values are determined and reported under the fund’s rules; it is not a promise of what an asset could be sold for in a particular circumstance. A report date identifies when information was prepared, not whether it reflects later changes.
What should you check before describing the structure?
Use these checks to separate documented facts from open questions. For each observation, the next action depends on what the documents actually say.
- Legal vehicle: Check which entity issues the shares, units or other interest. If its legal form is stated, record the form; if it is missing, leave it unresolved and look for the relevant formal definition.
- Property ownership: Check whether the documents name direct ownership or an entity holding property. If an intermediary is named, add it to the map; if the ownership route is unclear, do not infer it and request clarification.
- Decision-making: Check which party is assigned powers over investment decisions. If a board, manager or general partner is named, record the stated powers; if only a title appears, look for the provision that defines its authority.
- Oversight and custody: Check which organisations are named and what functions the documents assign them. If a role is specified, keep it distinct from decision-making; if the function is not explained, mark it as an open question.
- Borrowing: Check whether the documents identify borrowing at fund or subsidiary level. If they identify the borrower, add that entity to your notes; if they do not, do not assume borrowing sits at the fund level.
- Investor’s interest: Check whether the investor holds a share, unit, partnership interest or another stated interest. If the documents define it, use that wording; if the description is unclear, seek a formal explanation rather than calling it direct property ownership.
- Consistency: Check whether the same entities and relationships appear consistently across the current documents. If descriptions conflict, record both and ask which formal document or provision governs; if they agree, describe only what they establish.
These checks are not a scorecard. A more complicated map is not automatically a defect, and a simple map does not prove that every relevant detail is straightforward. Their purpose is to make the documented organisation visible and keep missing information visible too.
What can a property fund structure not tell you?
A stated structure cannot, on its own, tell you whether a fund fits your objectives, financial position, time horizon or tolerance for risk. It also does not establish a manager’s quality, a property’s future value, how easily an investment can be sold, or what an investor may receive. Those questions depend on the specific terms, assets, risks and personal circumstances.
Nor does the number of entities decide whether arrangements are effective. Several layers may reflect legal, tax, financing or operational choices; a direct-holding arrangement can still have complex terms. Think of the structure diagram as a set of labelled storage boxes: it shows where things are kept and how the boxes connect, but not the condition or usefulness of what is inside.
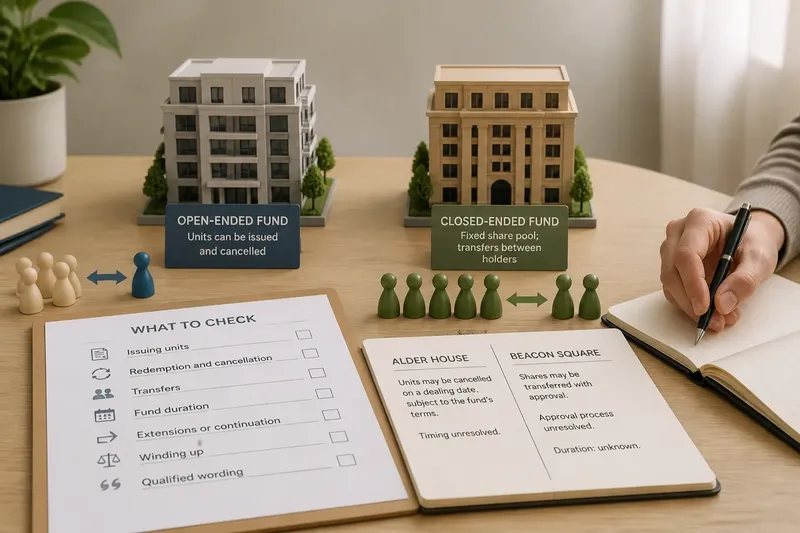
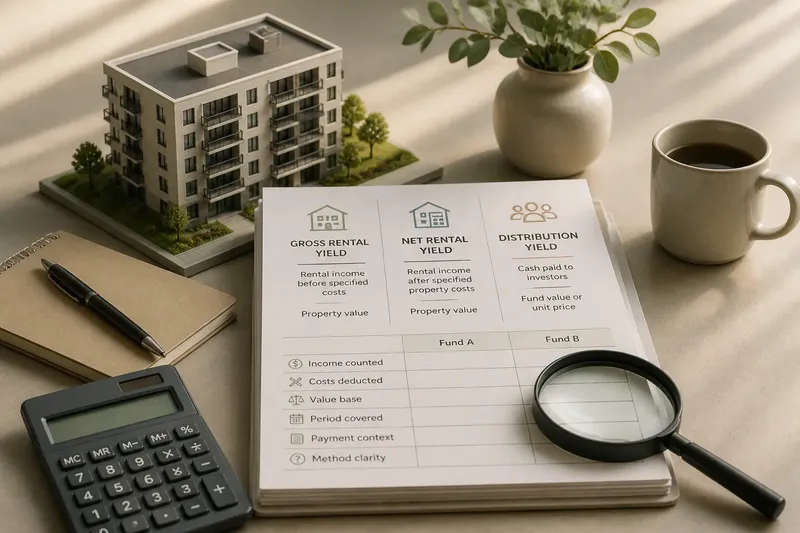
Keep legal form, fund framework and performance language distinct. Legal form describes the organisation. The fund’s framework covers matters such as how interests are issued or dealt with under its terms. Yield or return descriptions are separate and need to be read with their definitions, charges and risks.
Which questions do readers ask about property fund structure?
Does “property fund” mean the fund owns buildings directly?
Not necessarily. The fund may hold property through a subsidiary, another fund or a company that owns the assets. Trace the ownership chain in the formal documents before describing what the investor-facing vehicle holds.
Does a company, trust or partnership label show who makes decisions?
It identifies a legal form, but the governing documents set out decision-making powers. Look for the provisions naming the board, manager, trustee, general partner or other responsible party, and distinguish authority from oversight.
Can a structure label tell me whether a fund is suitable?
No. Suitability depends on personal circumstances and the fund’s specific terms, risks and objectives, not on the label alone. A qualified financial professional can help assess personal decisions where needed.
What should I do if the diagram and written description conflict?
Record the inconsistency and check the current formal documents rather than guessing which description is correct. If the issue remains material or unclear, ask the fund provider for a written explanation or consult a qualified legal professional.
Use property fund structure as a starting point for tracing documented relationships, not as a conclusion about an investment. Keep the entity map beside the exact terms that support it, and leave an explicit note wherever the documents do not settle a question. That makes later comparisons more accurate without turning an organisational label into a claim about suitability or outcomes.